Highlighted Holding: Haier Smart Home
10 min read
Third Quarter 2026 Highlighted Holding
Weak appliance demand has driven Haier’s shares lower. Yet its premium brands and continued investment are helping it gain market share, offering investors a stronger business at a lower valuation.
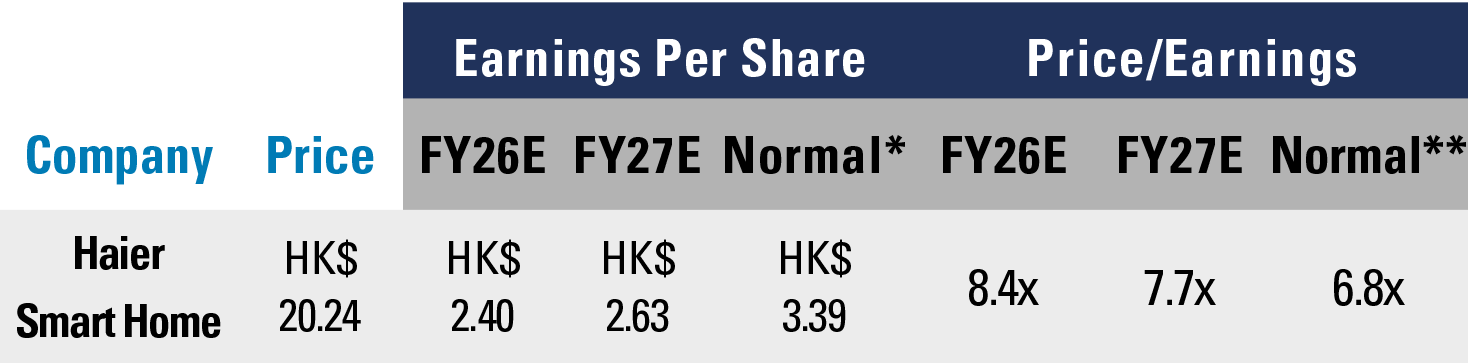 Fiscal year-end December 31.
*Pzena estimate of normal earnings.
**Globally adjusted price-to-normal multiple based on Hong Kong discount rate.
Source: S&P Capital IQ, Pzena analysis. Data as of September 30, 2026.
HIGHLIGHTED HOLDING: HAIER SMART HOME
Headquartered in China, Haier Smart Home is the world’s largest1 major home appliance manufacturer. Despite continued market share gains in China and the U.S., its two largest markets, sales and profits have stalled. Demand in China has fallen since the government scaled back appliance subsidies, while tariffs and a soft housing market have weighed on GE Appliances, its U.S. business. These headwinds, along with investors’ flight out of Chinese consumer stocks and into AI, have driven the stock down roughly 40% from its 2024 highs. In our view, at 6.8x our normal earnings estimate, the industry’s strongest franchise is priced for structural decline rather than a cyclical downturn.
CHINA’S PREMIUM LEADER
Founded in 1984 as a single factory in Qingdao, Haier is now one of China’s big three home appliance makers, along with Midea and Gree, and the most international of the three. It built its overseas business largely by buying established brands, including GE Appliances in the U.S., Fisher & Paykel in New Zealand, and Candy in Italy. China accounts for roughly half of its sales, and the U.S. for about a quarter (Exhibit 1).
Exhibit 1: Haier’s Sales by Region and Product, 2025
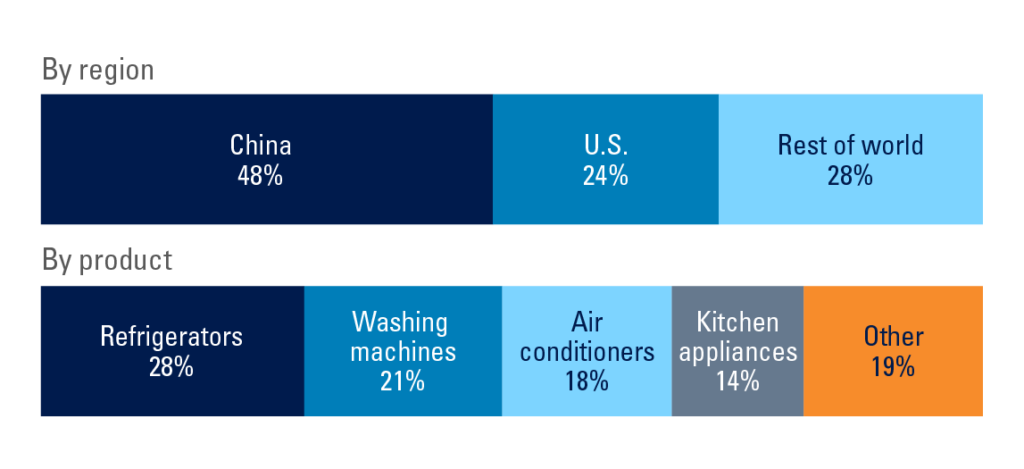
Source: Haier Smart Home, Pzena estimates.
In China, a handful of giants dominate refrigerators, washing machines, and air conditioners. The three largest in each category account for more than 70% of sales, and Haier alone sells roughly one of every two washing machines and refrigerators. Concentration and strong brands have supported pricing discipline, giving appliances one of the country’s best industry structures. Appliance makers have largely avoided the price wars that have battered industries such as electric cars and solar panels.
Haier has also led the premiumization of China’s appliance market. Its homegrown premium brand, Casarte, sells more than half of the refrigerators and nearly three-quarters of the washing machines priced above approximately $1,4002. That position reflects years of investment in product innovation and brand building, and it brings higher margins and steadier sales through downturns.
TRANSFORMING GE APPLIANCES
When Haier bought GE Appliances in 2016, years of underinvestment had left the business earning about 3% on sales, roughly a quarter of Whirlpool’s North American margin. Haier kept GE Appliances’ experienced American managers but gave them capital and shared its product technology and factory automation know-how. A Chinese owner and an American icon might easily have clashed. Instead, the partnership has worked remarkably well, and GE Appliances has even adopted its parent’s management system, which puts small teams in charge of individual product lines. The business has modernized its factories and brought out new products faster than its rivals.
GE Appliances is now the U.S. market leader, ahead of Whirlpool, LG, Samsung, and Electrolux, with products in half of all American homes. It has a particular edge over LG and Samsung with homebuilders, a channel it dominates along with Whirlpool because builders rely on delivery and installation networks that take decades to develop. Its own service network also helps keep customers loyal when an appliance needs repair or replacement.
CHINA’S POST-SUBSIDY SLUMP
China’s property slump has weighed on Haier’s home market for several years, cutting demand for appliances that typically go into new homes. In 2025, to support consumer spending, the government expanded an appliance trade-in subsidy that cut prices by up to 20% at checkout. Shoppers rushed to buy while the discount lasted, and sales jumped across the industry. Haier’s China revenue rose 9% in the first half of 2025 (Exhibit 2). That surge faded as funding ran low, and in 2026 the government cut the subsidy to 15% and narrowed it to fewer products. Haier’s China revenue fell 5% in the first half of 2026, while the industry’s retail sales dropped nearly 10%. The remaining subsidy is funded only through 2026, and investors fear that sales will fall further if the government does not renew it.
Exhibit 2: Haier’s China Sales Rose with Subsidies, Then Fell Back
Mainland China Revenue by Half
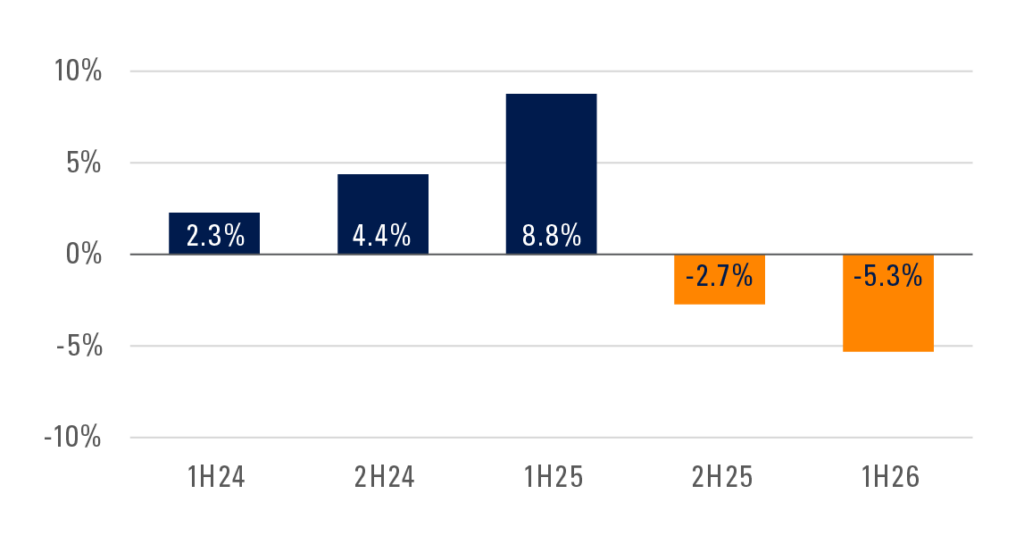 Source: Company reports, Pzena analysis.
When China ended its previous appliance subsidy program in 2011, Haier pulled ahead of its rivals. The industry took nearly two years to recover, but Haier’s revenue rose 8% and its operating profit 25% in 20123, as its distribution network and premium brands won customers from weaker competitors. Early signs suggest it is pulling ahead again. So far in 2026, Haier has increased its retail value share in China, and its domestic gross margin has risen despite lower sales and higher commodity costs. Casarte has done best, with retail sales down only 3%, because its wealthier buyers are less sensitive to price and relied less on the subsidy.
HOUSING AND TARIFFS PRESSURE THE U.S. BUSINESS
GE Appliances is contending with a weak appliance market, as housing activity remains depressed. Higher mortgage rates have created a pronounced “lock-in” effect, with most homeowners paying well below today’s rates and therefore reluctant to move. That lock-in effect has helped push existing-home sales to near 30-year lows, while new construction has provided little offset. The damage shows up more in profits than in units. Broken appliances are still being replaced, but those buyers tend to pick cheaper models. The high-end purchases that come with moving or remodeling have fallen furthest.
Tariffs have added a second, more direct pressure on profits by raising the cost of steel, components, and imported finished goods. Imported front-load washers are GE Appliances’ largest tariff exposure, and we estimate that, at peak rates, tariffs on those washers alone could absorb roughly a fifth of its U.S. operating profit. GE Appliances is responding with price increases and a $3 billion, five-year plan to expand U.S. production4.
Both headwinds are hurting GE Appliances’ rivals more, widening a lead GE has built through a decade of market share gains under Haier (Exhibit 3). The downturn has forced Whirlpool and Electrolux, the owner of Frigidaire, to raise capital. Whirlpool sold about $1.1 billion of new equity in February and suspended its dividend in May to pay down debt, while Electrolux raised about $1 billion from shareholders as part of a restructuring. Tariffs, meanwhile, weigh more heavily on LG and Samsung, which by Haier’s estimate import about 70% of what they sell in the U.S., against about 40% for GE Appliances.
Exhibit 3: Haier’s Market Share Gains, 2016–2025
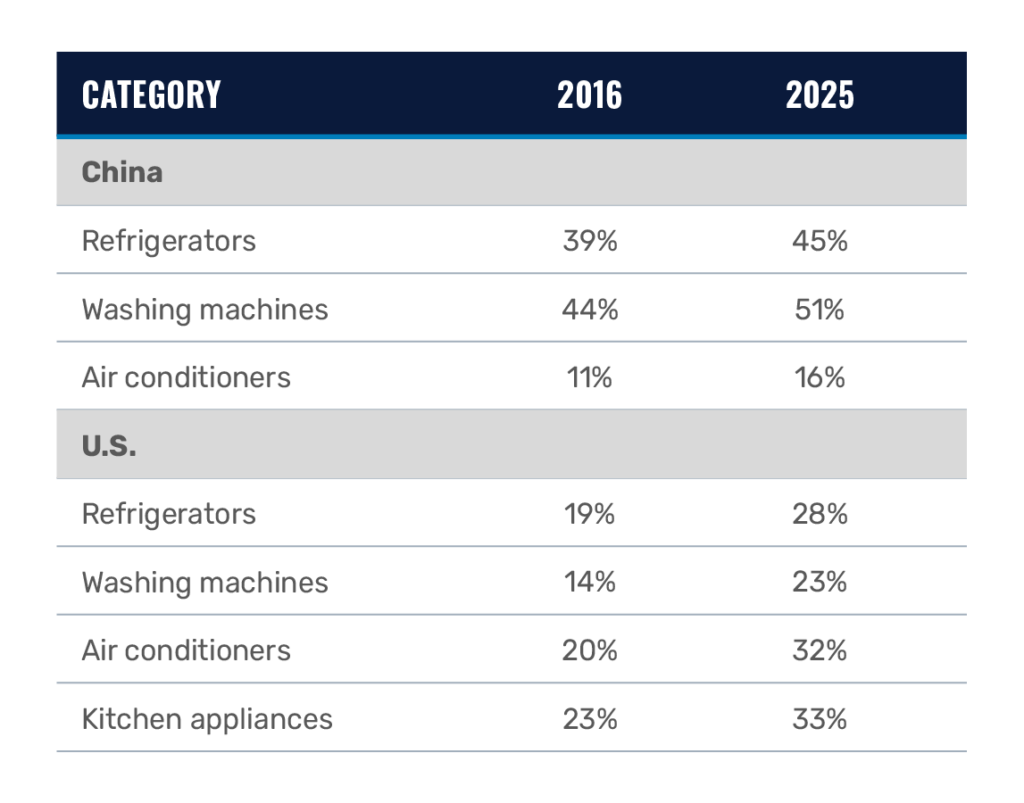 Source: Euromonitor International
Figures rounded to the nearest whole percentage point.
EARNINGS POWER INTACT
Haier’s operating profit has held up far better than its share price. Its operating margin has stayed at about 7% through the subsidy cut and tariffs, as cost savings in China and growth in other overseas markets offset weakness in the U.S. Our normal earnings estimate assumes a margin of only about 5.5%, slightly below Haier’s 10-year average. Further share gains, premiumization, or a housing recovery would lift earnings above it.
The main risks are a longer slump in China, if the subsidy lapses at year-end, and a deeper one in the U.S., if housing weakens further. Electrolux’s new partnership with Midea could also add competition in the U.S., though it will take years to reach scale. Haier’s net cash, equal to about a sixth of its market value, means it can ride out a longer slump and keep investing, while indebted rivals have had to pull back on investment. It also pays out more than half its earnings as dividends and is buying back shares.
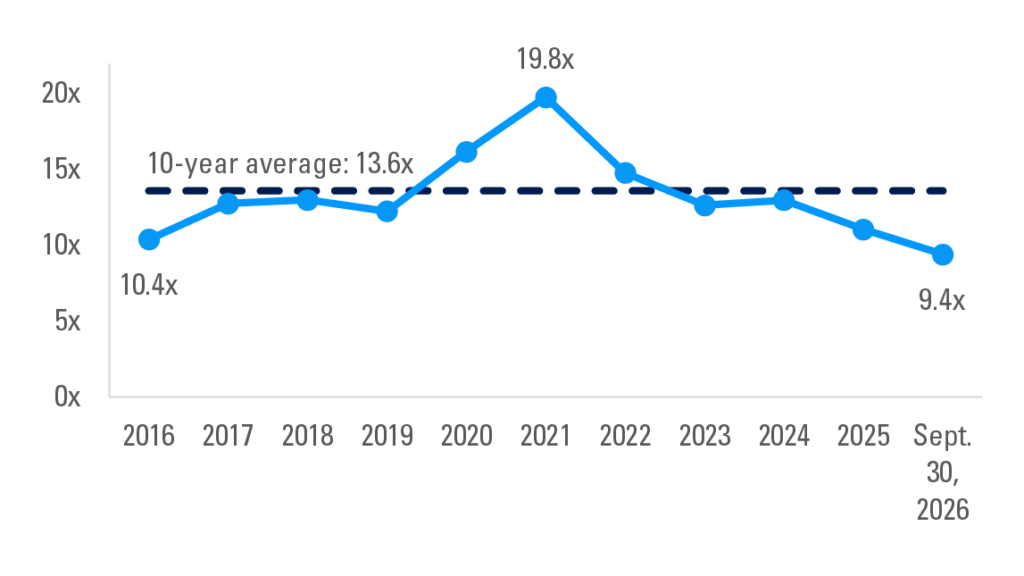
Yet Haier’s shares trade at about 9x forward earnings, well below their 10-year average of nearly 14x (Exhibit 4). We believe the company’s competitive advantages are growing, not shrinking, and long-term investors can now buy a far stronger Haier at a lower valuation than at almost any point in the past decade.
Exhibit 4: Haier’s Valuation Sits Well Below Its 10-Year Average
Price to Forward Earnings
 Source: CapIQ and Pzena
Footnotes
- By retail volume of major appliances. Source: Euromonitor International
- Source: Haier Smart Home 2026 Interim Report
- Source: S&P Capital IQ
- GE Appliances (August 2025)
Weak appliance demand has driven Haier’s shares lower. Yet its premium brands and continued investment are helping it gain market share, offering investors a stronger business at a lower valuation.
Further Information
These materials are intended solely for informational purposes. The views expressed reflect the current views of Pzena Investment Management (“PIM”) as of the date hereof and are subject to change. PIM is a registered investment adviser registered with the United States Securities and Exchange Commission. PIM does not undertake to advise you of any changes in the views expressed herein. There is no guarantee that any projection, forecast, or opinion in this material will be realized. Past performance does not predict future returns.
All investments involve risk, including loss of principal. Investments may be in a variety of currencies and therefore changes in rates of exchange between currencies may cause the value of investments to decrease or increase. The price of equity securities may rise or fall because of economic or political changes or changes in a company’s financial condition, sometimes rapidly or unpredictably. Investments in foreign securities involve political, economic and currency risks, greater volatility and differences in accounting methods. These risks are greater for investments in Emerging Markets. Investments in small-cap or mid-cap companies involve additional risks such as limited liquidity and greater volatility than larger companies. PIM’s strategies emphasize a “value” style of investing, which targets undervalued companies with characteristics for improved valuations. This style of investing is subject to the risk that the valuations never improve or that returns on “value” securities may not move in tandem with the returns on other styles of investing or the stock market in general.
This document does not constitute a current or past recommendation, an offer, or solicitation of an offer to purchase any securities or provide investment advisory services and should not be construed as such. The information contained herein is general in nature and does not constitute legal, tax, or investment advice. PIM does not make any warranty, express or implied, as to the information’s accuracy or completeness. Prospective investors are encouraged to consult their own professional advisers as to the implications of making an investment in any securities or investment advisory services.
The specific portfolio securities discussed in this presentation are included for illustrative purposes only and were selected based on their ability to help you better understand our investment process. They were selected from securities in one or more of our strategies and were not selected based on performance. PIM is a discretionary investment manager and does not make “recommendations” to buy or sell any securities. There is no assurance that any securities discussed herein remain in our portfolios at the time you receive this presentation or that securities sold have not been repurchased.
Haier Smart Home was held in our Emerging Markets Focused Value, Emerging Markets Select Value, Global Focused Value, International Focused Value, International Value, and other strategies during the third quarter of 2026.
For EU Investors Only:
This marketing communication is issued by Pzena Investment Management Europe Limited (“PIM Europe”). PIM Europe (No. C457984) is authorised and regulated by the Central Bank of Ireland as a UCITS management company (pursuant to the European Communities (Undertakings for Collective Investment in Transferable Securities) Regulations, 2011, as amended), with additional authorisation for management of portfolios of investments, in accordance with mandates given by investors on a discretionary, client-by-client basis, where such portfolios include one or more of the investment instruments listed in Section C of the Annex to the MiFID (Markets in Financial Instruments) Regulations 2017 (S.I. No. 375 of 2017), as amended), and investment advice concerning one or more of the instruments listed in Annex I, Section C to Directive 2014/65/EU (MiFID II). PIM Europe is registered in Ireland with the Companies Registration Office (No. 699811), with its registered office at Riverside One, Sir John Rogerson’s Quay, Dublin, 2, Ireland. Past performance is not indicative of future results. The value of your investment may go down as well as up, and you may not receive upon redemption the full amount of your original investment. The views and statements contained herein are those of Pzena Investment Management and are based on internal research.
For Australia and New Zealand Investors Only:
This document has been prepared and issued by Pzena Investment Management, LLC (ARBN 108 743 415), a limited liability company (“Pzena”). Pzena is regulated by the Securities and Exchange Commission (SEC) under U.S. laws, which differ from Australian laws. Pzena is exempt from the requirement to hold an Australian financial services license in Australia in accordance with ASIC Class Order CO 03/1100 and the transitional relief under ASIC Corporations (Repeal and Transitional) Instrument 2016/396, extended through 31 March 2027 by ASIC Corporations (Foreign Financial Services Providers) Instrument 2025/798. Pzena offers financial services in Australia to ‘wholesale clients’ only pursuant to that exemption. This document is not intended to be distributed or passed on, directly or indirectly, to any other class of persons in Australia.
In New Zealand, any offer is limited to ‘wholesale investors’ within the meaning of clause 3(2) of Schedule 1 of the Financial Markets Conduct Act 2013 (‘FMCA’). This document is not to be treated as an offer, and is not capable of acceptance by, any person in New Zealand who is not a Wholesale Investor.
For South African Investors Only:
The Pzena Emerging Markets Focused Value Fund, Pzena Emerging Markets Select Value Fund, Pzena Global Focused Value Fund, Pzena Global Value Fund are registered and approved under section 65 of CISCA.
Collective Investment Schemes in Securities (CIS) should be considered as medium- to long-term investments. The value may go up as well as down and past performance is not necessarily a guide to future performance. CISs are traded at the ruling price and can engage in scrip lending and borrowing. A schedule of fees, charges and maximum commissions is available on request from the Manager. A CIS may be closed to new investors in order for it to be managed more efficiently in accordance with its mandate. There is no guarantee in respect of capital or returns in a portfolio. Representative Office: Prescient Management Company (RF) (Pty) Ltd is registered and approved under the Collective Investment Schemes Control Act (No.45 of 2002). For any additional information such as fund prices, fees, brochures, minimum disclosure documents and application forms please go to www.pzena.com.
© Pzena Investment Management, LLC, 2026. All rights reserved.